

Pension assets climb to US$3.41 billion as contribution arrears approach US$149 million, while a quarter of a million members remain linked to unclaimed benefits…
By Shingirai Vambe
Zimbabwe’s pension industry is getting bigger, richer and increasingly sophisticated on paper, but behind the billions of dollars in assets is a far less comfortable story of pensioners waiting for money, employers failing to remit contributions on time, benefits going unclaimed and thousands of retirees having their payments suspended, the Post can Report.
The latest pension sector report from the Insurance and Pensions Commission (IPEC) provides a revealing snapshot of an industry holding US$3.41 billion in assets as at March 31, 2026, a 10 percent increase from US$3.11 billion at the end of December 2025.
Yet, at the same time, pension contribution arrears rose by 18 percent to US$148.96 million, up from US$126.26 million in just three months.
It is this contradiction that should concern workers approaching retirement and pensioners already dependent on their benefits: the industry is accumulating assets and generating investment returns, while money that should have been flowing into individual pension accounts remains outstanding.
IPEC’s latest report does not suggest that the entire pension industry is failing. In fact, several indicators point to significant recovery and growth.
But buried in the numbers are warning signs that cannot easily be dismissed.
At March 31, Zimbabwe’s pension funds controlled assets worth approximately US$3.41 billion, up from US$3.11 billion three months earlier.
The sector’s recovery is even more striking when viewed over five years.
Assets stood at US$3.43 billion in March 2022 before falling sharply to US$1.66 billion in March 2024, largely because exchange-rate depreciation eroded their United States-dollar value.
They have since recovered, reaching US$3.41 billion by March 2026, a 105 percent increase from the March 2024 trough.
Property remains the dominant component of the portfolio.
Investment properties and property units were valued at US$1.38 billion, accounting for about 40 percent of total assets.
Quoted equities also surged, rising 36 percent from US$698.73 million to US$948.18 million.
Together with pooled investments and other major asset classes, pension funds are increasingly positioned as significant institutional investors in Zimbabwe’s economy, showing pension money is not merely sitting in bank accounts, rather financing property, equities, businesses and other investments.
IPEC Commisioner, Dr Grace Muradzikwa responded and said, the pension industry is an important part of the country’s financial architecture, and the performance of those investments ultimately matters to the worker whose monthly contribution built the fund.
While the asset base is expanding, pension contribution arrears are moving in the opposite direction.
Employers owed pension funds US$148.96 million by March 2026, compared with US$126.26 million at the end of December.
Foreign-currency-denominated contribution arrears reached US$60.52 million, up 15 percent from US$52.6 million in December 2025.
IPEC says it continues to engage employers to ensure contributions are remitted on time and has warned that enforcement measures, including garnishment, may be used against persistent offenders.
For an ordinary worker, however, an employer’s failure to remit pension deductions is not an accounting technicality, It can translate into years of lost retirement savings. The employee may see the pension deduction on a payslip and reasonably assume that the money has been invested on their behalf.
But if the employer withholds the deduction without promptly remitting it to the pension fund, the worker’s retirement security is potentially compromised.
The Report by IPEC strikes, on the number of members associated with unclaimed benefits. By March 2026, 250,435 members were recorded under unclaimed benefits, up from 104,846 in December 2025, a 139 percent increase.
The dramatic increase was largely caused by the Construction Industries Pension Fund (CIPF), which reclassified 146,861 dormant members into the unclaimed-benefits register following a corrective directive.
But the numbers expose a deeper problem with pension administration: people can work, contribute, leave employment and disappear from the system without successfully collecting what they have accumulated.
IPEC says the problems include incomplete enrolment records, variations in names, failure to update records after members leave employment and information losses during legacy system migrations and the age profile of those benefits is particularly revealing 38percent of unclaimed benefits are between six and 10 years old, while another 27 percent are more than 10 years old in a country where many retirees survive on modest incomes, leaving retirement benefits unclaimed for a decade can have profound consequences.
The issue becomes even more uncomfortable when viewed alongside the amount actually transferred to the Guardian Fund during the quarter.
Despite the large unclaimed liability and membership, only US$16,002, relating to 11 members, was remitted to the Guardian Fund during the period.
IPEC says benefits outstanding beyond five years should ultimately be transferred to the Policyholder and Pension Scheme Members Protection Fund under the amended law, although the fund is still being institutionalised.
The regulator has specifically raised concerns about self-administered schemes, which accounted for 56 percent of the total unclaimed-benefits liability, and has directed compliance action against those funds and their administrators.
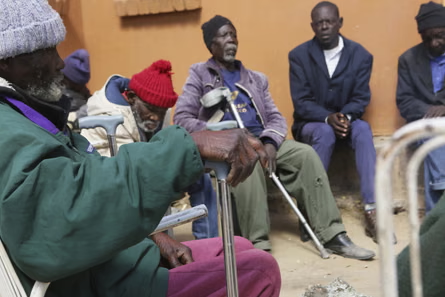
There is another group whose predicament is equally revealing, that of suspended pensioners.
IPEC recorded 12,931 suspended pensioners at March 31, with a total liability of about US$6 million.
The number had declined from 13,624 in December 2025, suggesting that some progress is being made in tracing beneficiaries and restoring payments but 12,931 is still a substantial number of people, these are not necessarily people who have lost their pensions permanently rather, their payments have been suspended, often because funds require confirmation that a pensioner is still alive or otherwise eligible.
IPEC now wants pension administrators to move away from a passive approach in which pensioners are simply required to produce documents proving their existence.
The regulator recommends digital submissions through email, WhatsApp and video, third-party attestations for incapacitated pensioners, cross-checking with the Registrar-General’s deaths register and even field visits before benefits are suspended.
During the first three months of 2026, pension funds recorded US$2.56 million in commutations.
The largest reason was retirement, accounting for 36 percent, followed by withdrawals at 24 percent and balances below the minimum threshold at 20 percent.
IPEC warns that although commutations provide vital emergency relief, they erode long-term retirement capital and threaten future elderly security, and this warning deserves wider public attention.
Over and above, pension funds generated US$313.49 million in total income during the three months ended March 2026, a 74 percent increase from US$180.13 million during the comparable period last year while US$216.07 million came from investments, Fair-value gains alone contributed US$160.67 million.
IPEC says pension funds need to distribute income from foreign-currency-generating investments fairly in order to strengthen member benefits and improve long-term savings outcomes.
For pensioners, the headline is therefore not necessarily how much money the industry has, it is how much of that wealth ultimately reaches the people whose labour and contributions created it.
Zimbabwe has 975 registered occupational pension funds, of which 477 were active and 498 inactive as at March 31.
The industry had more than 1.16 million members including beneficiaries, with 36,282 pensioners, 373,921 deferred pensioners, 12,931 suspended pensioners and 250,435 members associated with unclaimed benefits.
These figures reveal an industry operating at enormous scale.
But growth in the pension industry cannot be measured only by the size of its investment portfolio.
It must also be measured by whether an elderly former worker receives their pension on time, whether a surviving spouse can access benefits without bureaucratic obstacles, whether employers remit contributions faithfully, whether records can survive changes in technology and currency, and whether a retiree can live with dignity after decades of work.


More Stories
Tax, Trust and Financial Literacy- Zimbabwe’s Long Struggle With the Obligations of a Modern Economy
Birthday, Power and Politics- Enter Munhumutapa Day
Chiweshe Case Raises Dust, Puts Judiciary Under Scrutiny